
Buying Jewelry for Personal Use or Investment: How to Understand the Financial Difference
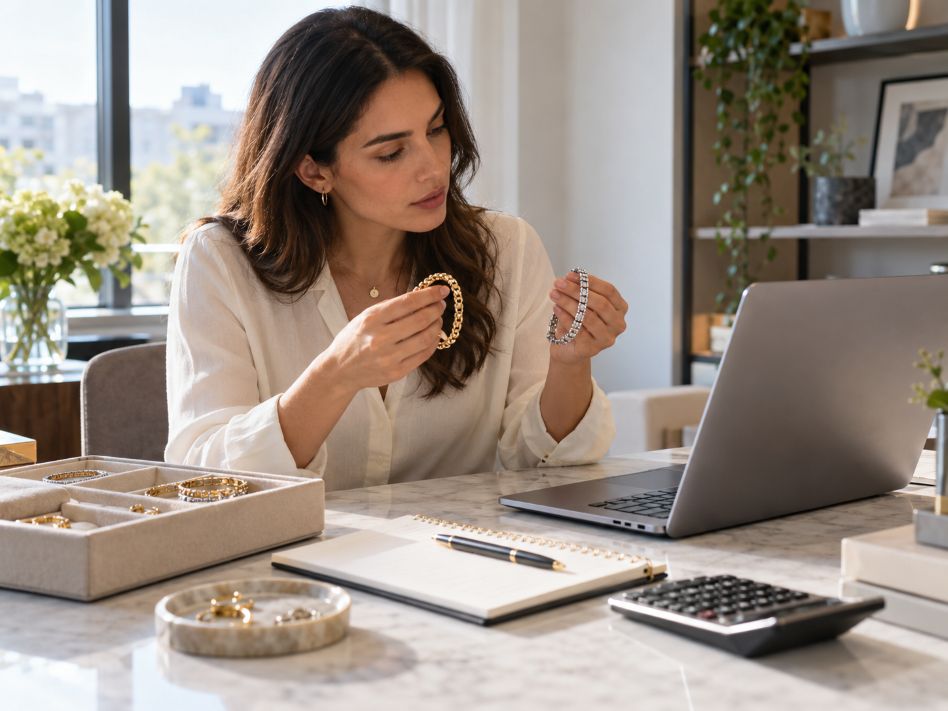
Jewelry can carry several kinds of value, but the price paid at a store does not automatically become an investment value. Retail prices can reflect materials, design, manufacturing, branding, distribution, and seller margins. By contrast, resale value depends on what another buyer is willing to pay. Jewelers Mutual explains that retail replacement value is generally different from resale value, which is an important distinction for anyone considering jewelry as a financial asset.
This difference matters when shopping for fashion-oriented gemstone jewelry, including pieces from Aqua Gold. The collection includes items made with materials such as sterling silver, plated metals, moissanite, and cubic zirconia. A buyer may value such jewelry mainly for its appearance, style, and personal use rather than expecting the purchase price to appreciate over time. Product specifications therefore matter more than assumptions based on appearance alone.
Why Retail Price and Investment Value Are Different
A piece of jewelry can be expensive without behaving like a conventional investment. Retail pricing has to cover more than the raw metal and gemstone content. Labor, design, packaging, marketing, inventory, and operating costs may all influence what consumers ultimately pay.
Intrinsic material value looks at the underlying materials instead. For precious metals, factors such as metal type, purity, and weight are important. Federal Trade Commission consumer guidance advises shoppers to understand markings and terminology used for gold, silver, and platinum because these descriptions indicate the composition and quality of the item.
Gemstones introduce another layer of complexity. Gemological Institute of America research explains that gemstone prices can be influenced by characteristics such as color, clarity, size, origin, shape, and cutting quality. This means two visually similar pieces may have very different material values.
A Step-by-Step Guide to Evaluating Jewelry Purchases
A practical evaluation starts by separating the reasons for buying the jewelry from expectations about future financial returns. These steps can help consumers examine a purchase more carefully.
1. Identify the Metal and Gemstone Materials
Start with the product description. Determine whether the piece uses solid gold, sterling silver, stainless steel, plated metal, or another material. Then identify whether any stones are natural, laboratory-created, simulated, or treated.
The Federal Trade Commission notes that jewelry sellers should accurately describe important characteristics such as metallic content, gemstone type, treatments, size, weight, and quality. Consumers should therefore read specifications rather than judge value mainly from photographs or appearance.
2. Review the Product Specifications
Look beyond broad descriptions such as gold, silver, or gemstone jewelry. Check purity, plating, stone type, dimensions, weight, and construction when that information is available.
For gemstones, treatments can also matter. Federal Trade Commission guidance explains that certain gemstone treatments should be disclosed when they affect value, require special care, or are not permanent. These details may influence durability, maintenance needs, and potential resale interest.
3. Compare Retail Prices Carefully
Compare similar products using comparable specifications. A lower-priced piece may use different metals, thinner construction, smaller stones, or alternative gemstones. A higher price does not necessarily mean the item will have stronger resale performance.
This comparison is especially useful for jewelry purchased mainly for fashion. Personal utility has real value to the buyer. Someone may happily pay for a design they expect to wear regularly even when there is little expectation of recovering the full purchase price later.
4. Investigate the Resale Market
If investment potential matters, examine what comparable jewelry actually sells for on secondary markets. Asking prices alone provide limited information. Buyers should consider demand, condition, rarity, brand recognition, material value, and current fashion preferences.
Guidance from the Gemological Institute of America recommends considering fair market value when selling jewelry. A professional appraisal may consider gemstone quality, market availability, local demand, and the desirability of a particular piece. Fashion can also affect the price buyers are prepared to pay.
5. Account for Maintenance and Transaction Costs
Ownership can create ongoing expenses. Jewelry may require cleaning, repairs, replating, resizing, stone tightening, or insurance. Selling can also involve appraisal costs, dealer margins, marketplace fees, or other transaction expenses.
Insurance valuations require particular care. Jewelers Mutual notes that an insurance appraisal generally estimates the cost of replacing a piece with something comparable. That figure should not be treated as the amount an owner could expect to receive from selling it.
Decide What Kind of Value Matters to You
A personal jewelry purchase does not need to generate a financial return to be worthwhile. Wearability, appearance, sentiment, durability, and enjoyment can all be reasonable reasons to buy a piece. The key is recognizing that these benefits are different from investment performance.
Someone evaluating jewelry primarily as an investment needs a different standard. Material quality, documented provenance, rarity, market demand, liquidity, resale costs, and realistic selling prices become more important than the original retail price. Buyers can also compare these characteristics with more conventional low-risk investment options, where potential returns, access to funds, and the possibility of capital loss are assessed more directly.
Jewelry can therefore occupy two very different roles. One piece may be an enjoyable accessory that provides years of personal use, while another may be purchased partly because of its collectible or material value. Understanding that distinction helps buyers set realistic expectations, compare products more carefully, and avoid assuming that an attractive retail purchase will automatically become a profitable financial asset.


 Homeownership is one of the most significant investments most people make. Protecting that investment ensures peace of mind and long-term financial stability. In Lubbock, mortgage providers like Herring Bank offer more than just home loans—they provide opportunities to bundle insurance with mortgages, delivering unique benefits that many homeowners might overlook.
 Property insurance is a critical aspect of real estate ownership in Costa Rica. With its diverse landscape, ranging from lush rainforests to pristine beaches, the country offers incredible opportunities for international buyers. However, understanding the intricacies of property insurance can be daunting without proper guidance.
 Maintaining a lead in the often changing fields of finance and insurance depends on this. To satisfy changing needs of its customers, Trident Insurance is developing its products. Integrating the most recent technologies and ideas helps Trident to make sure that its insurance products stay relevant and efficient in a market undergoing changes.


 The high-risk tag describing a driver pertains to that person’s bad or poor driving records. They even include those who have been convicted and served jail terms for driving under the influence (DUI) of liquor or Driving Without Insurance (DWI). Teenage drivers represent a large sector of this group, generally having the highest accident rates and moving violations when taking their vehicles on the road.
 Insurance companies reserve the right to refuse to give

 When contemplating on your financial security including that of your family’s, the most common advice you will receive is about a variety of insurance coverages. The most basic of course is a health insurance policy, which most large companies provide to their employees. A
 A
 This policy will relieve you of financial worries in case a long term illness or accident prevents you from generating income to help you live comfortably/ However, this policy must be arranged while you are still in the best of health and physical condition. Moreover, the insurance company will also take into consideration your present occupation and the degree of disability risks you face in performing your job.

